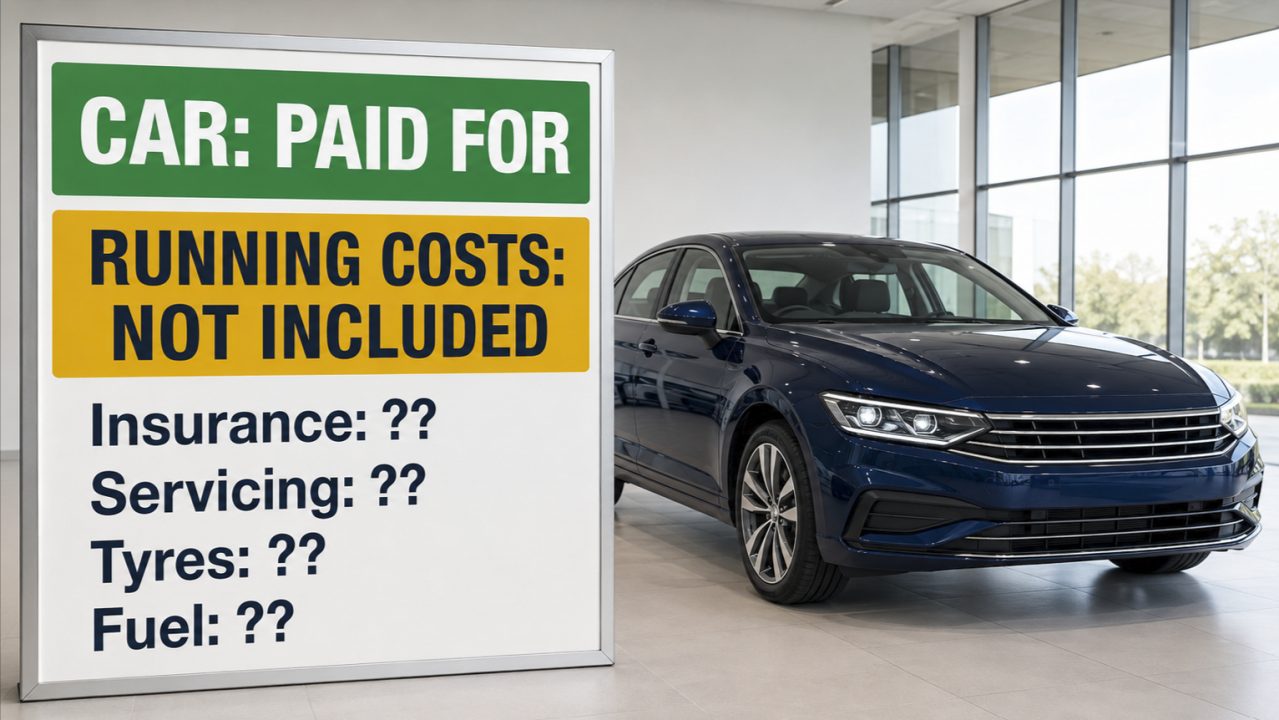
The purchase was approved. The model was debated. The price was negotiated. Even the colour received more attention than it deserved.
But there is no budget for the insurance, tax, servicing, tyres or fuel.
It sounds ridiculous. Yet I have worked on plenty of projects and programmes approved in much the same way.
The cost of buying or creating something was examined in detail. The cost of keeping it useful was underestimated, left until later, or quietly placed in that familiar corporate cost centre: Somebody Else's Problem.
This is why two rather unfashionable terms still matter: capex and opex.
What are capex and opex?
Capex, or capital expenditure, generally buys, creates or substantially improves something expected to provide value over more than one accounting period.
Opex, or operating expenditure, pays for the day-to-day cost of operating, supporting and maintaining it.
In simple car terms:
- Buying the car is generally capex.
- Insurance, tax, fuel and routine servicing are generally opex.
- A substantial improvement may be capex.
- Tyres, wiper blades and normal repairs are generally opex.
The words generally and may matter. The exact treatment depends on the organisation, the item and its accounting policies. Finance should make that decision.
But Finance will classify it is not the same as we can leave it out. Every cost still needs to be identified, estimated, funded and owned.
Where did the running costs go?
Capex gets all the attention. It buys the shiny new thing. It has a business case, a budget and a delivery date. Someone may even cut a ribbon.
Opex arrives afterwards. It pays for the people, training, consumables, licences, support, maintenance, compliance and future upgrades needed to keep that shiny new thing useful.
Those costs often sit in another budget, another financial year or another department.
Look beyond the purchase price
A simple table can expose the gap before approval. What will it cost to buy, run, improve and eventually replace?
| Cost | Build / Buy | Run | Later | Owner |
|---|---|---|---|---|
| Purchase or development | £ | Project | ||
| Preparation and implementation | £ | Project | ||
| People and training | £ | £ | £ | Named owner |
| Support and maintenance | £ | £ | Named owner | |
| Consumables, licences and usage | £ | £ | Named owner | |
| Enhancements and upgrades | £ | Business owner | ||
| Replacement or closure | £ | Named owner |
Estimate it. State the assumptions. Name the owner. Then refine it. The purchase price is only the first column.
The first figures will be estimates. That is fine. State the assumptions. Test them. Refine them as more becomes known.
A wrong estimate can be challenged. A missing cost sits quietly until it becomes a surprise.
Estimating those figures is another challenge. I set out twelve practical ways to estimate work using measurement, comparisons, historical data, expert judgement, ranges and other methods.
Six questions before handing over the keys
- What will it cost to buy or create?
- What will it cost to make ready for use?
- What will it cost to run and maintain each year?
- What happens to those costs as demand grows?
- Who owns the budget after the project closes?
- What will it cost to replace, retire or switch off?
None of these costs should be a surprise. They just need to be included in the conversation before everyone admires the new car and the project team hands over the keys.
Would you tax a car before it had been built?
Probably not. So why do organisations sometimes buy CRM or ERP licences for everyone before the system is ready for them?
It is an easy trap. At the start of a programme, suppliers often ask how many users will need licences. That is a fair question. The better question is who needs access, and when. Because not every user needs a licence on day one.
Early on you may only need the project team, the key users, the process owners, the testers, the trainers and the system administrators. The wider user base may not need access until pilot, UAT, training, rollout or go-live.
As a simple illustration: 50 users at around £80 per user per month is about £4,000 per month. That is nearly £50,000 a year before VAT, discounts, implementation costs, support or add-ons. So if 30 of those users do not need access until training or go-live, why pay for them months earlier?
A better approach is to map licences against the delivery plan. Who needs what? When do they need it? For what purpose? That gives you more than a licence plan. It gives you a cash flow plan, and sometimes that is the difference between controlled investment and quietly burning money in the background.
Buy what you need when you need it. Not what someone assumes you might eventually use. Nobody on the supplier side will point that out, because it is not their money, and nobody on the internal side will point it out, because they do not know it is a choice.
Capex buys the car. Opex provides the insurance, servicing, tyres and fuel.
Pressure-test the costs before they are signed off
The Payback Checker takes your cost and benefit figures, a supplier quote is enough to start, and gives you payback period, NPV, ROI, a capex and opex split and a cost of doing nothing comparison as you type. Outline numbers for a draft business case in an hour, not weeks.
Use the Payback Checker Read the FAQ